Your salary stops.
Your rent does not.
Neither do groceries, utilities, insurance, debt payments or other essential bills.
That is why the first financial question after losing a job is not:
“How quickly can I find another one?”
It is:
“How much time can my current finances buy me?”
That number is your financial runway.
Someone with twelve months of runway is in a very different position from someone with six weeks.
So the right response to job loss is not automatically to cancel everything, sell investments and cut life down to the absolute minimum.
First calculate the situation.
Then respond proportionately.
First: Find Out Exactly How Much Money You Have
Before cutting expenses, establish your financial starting point.
Create a simple inventory.
Cash available now
Include money you can actually access, such as:
- checking or current-account cash;
- savings;
- emergency savings.
Confirmed money still coming
This might include:
- final salary;
- accrued pay that has been confirmed;
- confirmed severance;
- other reliable incoming payments.
Keep this separate from cash already in your account because timing matters.
Benefits or other income
If you may qualify for unemployment support, include it only after eligibility and the likely payment amount are reasonably confirmed.
Rules differ significantly by country, so check the official government system that applies to you.
Do not count uncertain money as guaranteed
Avoid treating the following as available resources:
- unused credit-card limits;
- hoped-for severance;
- speculative investment gains;
- retirement assets that may carry taxes, penalties or access restrictions;
- money somebody has informally promised but not confirmed.
Credit is borrowing capacity, not emergency savings.
A useful inventory therefore separates:
cash available now
from
money confirmed but not yet received
from
money you merely hope to receive.
That distinction reduces the risk of making a plan around money that never arrives.
Calculate Your Financial Runway
This is the central calculation.
Accessible Money ÷ Essential Monthly Expenses = Approximate Financial Runway
Suppose you have:
Accessible money: $12,000
Essential monthly expenses:
$3,000
Calculation:
$12,000 ÷ $3,000 = 4 months
You have approximately four months of financial runway.
This is a planning estimate, not a guarantee. Unexpected expenses can shorten it, while confirmed income or benefits can extend it.
Now suppose you review spending and reduce necessary monthly outgoings from:
$3,000
to:
$2,500
Your runway becomes:
$12,000 ÷ $2,500 = 4.8 months
Cutting $500 per month has effectively bought almost another month of time.
That is why runway is more useful than panic.
You are not cutting expenses simply because “unemployed people should spend less.”
You are measuring how each decision changes the amount of time available.
If you already have a dedicated reserve, this is exactly the situation your emergency fund was designed to help absorb.
Do not confuse longer runway with maximum deprivation, though.
The aim is sustainable financial survival, not making life unnecessarily miserable to produce the largest mathematical number.
Separate Essential, Adjustable and Optional Spending
After calculating your starting runway, divide spending into three categories.
Essential
These are costs that generally need to continue.
Examples include:
- housing;
- basic food;
- essential utilities;
- healthcare;
- necessary transportation;
- essential insurance;
- minimum required debt payments;
- essential family costs.
Adjustable
These are legitimate expenses where the amount may be reduced.
Examples include:
- grocery choices above the basic requirement;
- transportation choices;
- phone plans;
- useful but reducible subscriptions;
- discretionary household spending.
Optional
These are easier to pause temporarily if runway is short.
Examples include:
- entertainment subscriptions;
- expensive dining;
- nonessential shopping;
- luxury travel;
- upgrades;
- convenience spending.
The purpose is not to cancel everything automatically.
Focus first on reductions that meaningfully extend runway without creating disproportionate disruption.
A €10 subscription matters less than a €500 recurring commitment.
Which Bills Should You Prioritise?
Not every missed payment has the same consequences.
At a broad level, protecting basic financial functioning usually means prioritising things such as:
- housing;
- food;
- essential utilities;
- healthcare and essential insurance;
- necessary transportation;
- legally required obligations.
Debt also requires attention, but debt-priority rules differ by jurisdiction and type of obligation.
Do not simply ignore a bill because cash is tight.
If you believe you may struggle to pay a lender or provider, contacting them early may give you more information or options than waiting until the payment is already missed.
Do not assume hardship arrangements are guaranteed.
The practical principle is simply:
Protect the expenses whose failure would create the fastest or most serious consequences.
Should You Use Your Emergency Fund?
Yes.
Job loss is exactly the kind of disruption an emergency fund is designed to help absorb.
Using it is not failure.
The important distinction is between:
using it deliberately
and
draining it without knowing what comes next.
Instead of thinking:
“I’ve already spent $4,000 of my emergency fund.”
think:
“At my current spending level, the remaining reserve gives me approximately five months before I need another source of income or a larger financial change.”
That is a much more useful way to manage the fund.
The dedicated Crown Altessa guide to how much emergency fund you need covers reserve sizing in more detail. Here, the key point is simpler: once employment income stops, that cash becomes part of your runway.
Should You Stop Investing After Losing Your Job?
There is no universal answer.
Preserving liquidity may temporarily become more important when regular employment income disappears.
The decision depends on factors such as:
- your current runway;
- emergency savings;
- expected length of the income gap;
- debt obligations;
- other household income;
- employer matching where relevant;
- tax consequences;
- restrictions attached to retirement accounts.
Someone with twelve months of liquid savings may make a different decision from someone with six weeks.
The mistake is continuing aggressive investing while simultaneously becoming short of cash for essential bills.
Equally, someone with a long runway should not assume job loss means every investment contribution must automatically stop.
This is one reason separating cash from investing matters. Liquidity and long-term growth have different jobs.
Should You Sell Investments to Pay Your Bills?
Stopping new investment contributions and selling existing investments are two different decisions.
Before selling, consider the broader sequence:
- available cash;
- confirmed incoming resources;
- realistic expense reductions;
- benefits or other income;
- then whether investment assets need to be accessed.
This is not a universal financial rule. It is a way to slow the decision down.
Selling investments can create consequences such as:
- locking in market losses;
- realising taxable gains;
- giving up future growth;
- creating transaction or account complications.
Retirement accounts deserve extra caution because withdrawals may involve taxes, penalties or long-term consequences depending on the jurisdiction and account type.
Do not treat retirement money as ordinary emergency cash unless you understand the consequences.
What Should You Do About Debt?
Job loss can temporarily change the objective.
Before income stops, your goal may have been:
“Pay this debt down as quickly as possible.”
During unemployment, the more immediate objective may become:
“Maintain financial stability and avoid unnecessary deterioration.”
That can mean distinguishing between:
required or minimum payments
and
voluntary accelerated repayment.
If you were paying an extra $500 each month toward a loan while employed, continuing that exact strategy may no longer make sense if it shortens your runway substantially.
That does not mean debt becomes unimportant.
It means liquidity becomes more valuable during an income interruption.
If difficulty is likely, communicate with creditors early rather than simply stopping payment without explanation.
How Should You Treat Severance Pay?
A large lump sum can feel psychologically like extra money.
After job loss, it may actually be replacement income.
Suppose you receive:
$15,000 severance
and your essential spending is:
$3,000 per month.
Before tax or other considerations, that sum represents roughly:
five months of essential expenses.
Thinking of it as “$15,000 to spend” and thinking of it as “five months of runway” produce very different decisions.
Before allocating severance, establish:
- the amount you will actually receive after any applicable taxes;
- when the payment will arrive;
- whether it affects benefits in your jurisdiction;
- immediate obligations;
- your revised financial runway.
Do not build a plan around the gross headline amount if the spendable amount is lower.
What About Unemployment Benefits?
Check the official government system that applies to you as soon as possible.
Eligibility, application deadlines, waiting periods, benefit amounts and duration differ substantially by jurisdiction.
Two principles are broadly useful:
Do not assume benefits will arrive until eligibility and likely payment are reasonably confirmed.
And:
Do not delay checking or applying simply because you currently have savings.
Once the expected amount and timing are clearer, include them in your runway planning.
For example, if essential monthly costs are $3,000 and confirmed unemployment support covers part of that amount, your cash reserve may decline more slowly than the simple cash-only calculation suggested.
Do Not Forget Health Insurance and Other Employment Benefits
Employment may provide more than salary.
Depending on your country and employer, job loss can affect:
- health coverage;
- life insurance;
- disability insurance;
- employer retirement contributions;
- employer matching;
- company vehicle;
- transportation benefits;
- phone or internet benefits;
- other compensation.
Do not assume every benefit disappears immediately, and do not assume every benefit continues.
Review the actual rules.
Health insurance is especially jurisdiction-specific. In some countries it is closely tied to employment; in others it is not.
The financial cost of replacing a lost benefit belongs in your revised budget.
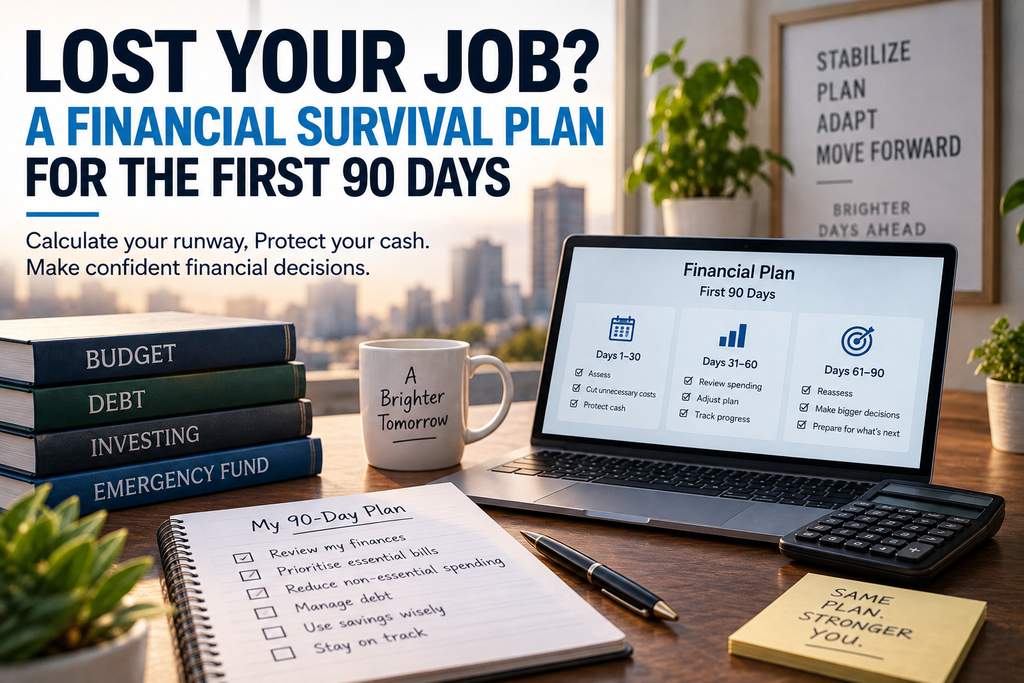
Your First 30 Days
During the first month, focus on establishing control rather than making every possible financial change.
- Confirm your final paycheck and any severance.
- Check and apply for applicable unemployment support.
- Inventory liquid resources.
- Calculate essential monthly expenses.
- Calculate your financial runway.
- Remove obvious low-value spending.
- Review debt obligations.
- Understand what happens to employment benefits.
- Avoid major new financial commitments.
- Begin replacing the lost income.
The last point belongs here only because runway is finite. The article is not a job-search guide, but every financial plan eventually depends on income being restored or replaced.
Days 31–60: Reassess
Do not create a 90-day plan on Day 1 and then never update it.
After roughly one month, compare:
expected spending
with
actual spending.
Then recalculate your runway.
Ask:
- Did I spend more or less than planned?
- Have benefits started?
- Has another income source appeared?
- Is the expected income-replacement timeline changing?
- Are my spending reductions sustainable?
- Do I need deeper cuts now?
Suppose your original estimate showed four months of runway.
After one month, you expected to have three months left.
But actual spending was lower and benefits began arriving.
Perhaps you now have 3.8 months.
Or the reverse may be true.
The point is that runway is a moving number.
Days 61–90: Decide Whether the Plan Needs to Change
If employment income has not been restored after two months, the remaining runway should drive the next decision.
Possible changes might include:
- stronger spending reductions;
- temporary alternative income;
- renegotiating certain financial commitments where possible;
- postponing major purchases;
- reconsidering housing or transportation costs if they are genuinely unsustainable;
- accessing investments only after considering the consequences.
Do not assume everyone should sell a car or move home after 90 days.
Someone with ten months remaining does not face the same urgency as someone approaching zero.
The shorter the runway becomes, the stronger the case for more substantial changes.
Three Different Job Losses, Three Different Responses
Job loss does not produce one universal financial prescription.
Case A: 12 Months of Runway
This person has substantial liquidity relative to essential spending.
Likely priorities:
- modest spending adjustment;
- preserve flexibility;
- review investments thoughtfully;
- avoid panic-driven decisions.
There is little reason to behave as though financial collapse is six weeks away.
Case B: 4 Months of Runway
This situation requires more active cash protection.
Likely priorities:
- stronger spending control;
- protect liquidity;
- reconsider voluntary debt overpayments;
- review new investment contributions;
- confirm benefits and other income.
Four months is meaningful time, but not unlimited time.
Case C: 6 Weeks of Runway
This is a substantially more urgent situation.
Likely priorities:
- immediate expense triage;
- rapid confirmation of benefits or support;
- early communication with creditors where payment problems may arise;
- aggressive focus on restoring income;
- avoiding new financial commitments.
The same advice would be inappropriate for all three people.
Runway determines urgency.
Common Financial Mistakes After Losing a Job
A few mistakes can shorten runway unnecessarily:
- refusing to use the emergency fund even though this is the event it was built for;
- maintaining pre-job-loss spending indefinitely;
- panic-selling investments immediately;
- continuing aggressive investing despite inadequate cash;
- treating credit limits as income;
- spending severance as though it were a windfall;
- ignoring bills;
- forgetting the value of lost employment benefits;
- failing to recalculate runway;
- making irreversible financial changes before understanding the actual situation.
The objective is not to eliminate every mistake.
It is to avoid decisions that create a second financial problem while dealing with the first.
Job Loss Financial Checklist
- Confirm final paycheck
- Confirm severance
- Check official benefit eligibility
- Calculate available cash
- Calculate essential expenses
- Calculate financial runway
- Reduce low-priority spending
- Review debt payments
- Review investment contributions
- Check health and insurance implications
- Review retirement accounts
- Avoid unnecessary new debt
- Recalculate runway monthly
A structured system can make this easier. Crown Altessa’s guide to managing your personal finances as a system explains why financial decisions become easier when money is organised by purpose rather than handled reactively.
Frequently Asked Questions
What Should I Do Financially Immediately After Losing My Job?
Confirm the money you actually have, calculate essential monthly expenses, check official benefit eligibility and calculate your financial runway.
Do this before making major irreversible financial decisions.
How Long Should My Savings Last After Losing My Job?
There is no universal target after the fact.
Calculate:
accessible money ÷ essential monthly expenses = approximate runway.
Someone with six weeks requires a more urgent response than someone with twelve months.
Should I Stop Investing If I Lose My Job?
Possibly, but not automatically.
Liquidity may become more important when employment income stops. Consider your runway, other household income, debt, emergency savings, employer matching and the type of investment account before changing contributions.
Should I Use My Emergency Fund After Losing My Job?
Yes. Job loss is one of the kinds of events an emergency fund is designed to absorb.
Use it as part of a deliberate runway plan rather than spending without tracking how long the reserve can last.
Should I Pay Off Debt With Severance Money?
There is no universal answer.
A large voluntary debt payment can reduce interest but also reduce liquidity. After job loss, maintaining sufficient cash for essential expenses may become more important than accelerating repayment.
Should I Sell Stocks After Losing My Job?
Not automatically.
Selling can create tax consequences, realised losses or lost future growth. First assess available cash, confirmed income, benefits, expenses and remaining runway.
How Often Should I Recalculate My Financial Runway?
Monthly is a useful starting rhythm during unemployment, and sooner if something material changes such as receiving severance, starting benefits, losing another household income source or sharply changing expenses.
Conclusion
Job loss turns liquidity into a scarce resource.
The first task is therefore not to make every possible financial change at once.
It is to determine:
- what resources you have;
- what you genuinely need each month;
- how long those resources can support you;
- what changes become appropriate as that runway gets shorter.
Someone with twelve months of runway should not automatically behave like someone with six weeks.
That is why the most useful number immediately after losing employment may not be your investment return, savings rate or net worth.
It may simply be:
“How many months can my current finances support me?”
If you want a broader beginner-friendly framework for organising savings, spending and financial priorities, Personal Finance Made Simple for Beginners covers those foundations in plain language.
My book on Gumroad:
https://ukandu0.gumroad.com/l/bteyh
Or on Amazon:
Feeling financially stuck?
When financial pressure becomes constant, long-term decisions start feeling emotionally heavy.
The Crown Altessa newsletter was created to help people rebuild clarity slowly and strategically through practical financial frameworks, long-term thinking, and structured decision-making insights.
Join the newsletter and receive:
• the free Financial Foundation Guide
• strategic financial insights
• practical tools for long-term stability
• frameworks designed to reduce financial overwhelm
Start building financial clarity one step at a time.