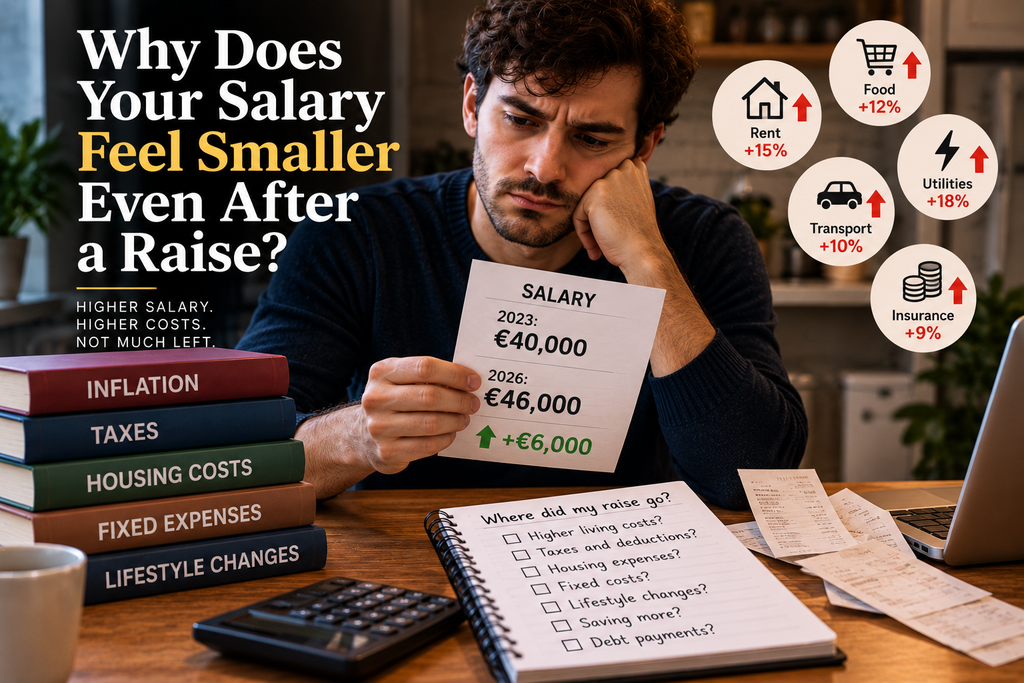
Three years ago:
Salary: €40,000
Today:
Salary: €46,000
That is €6,000 more per year.
So why does your bank account not feel €6,000 better? Why are you still watching grocery prices? Why does saving not feel easier? Why does a night out seem noticeably more expensive?
A higher salary and a richer life are not the same thing.
The missing piece is what happened to the cost of your life while your income was rising.
The Short Answer: Your Salary Grew, but So Did the Cost of Living
A pay raise increases your nominal income: the number attached to your salary.
What matters in daily life, however, is what that income can buy after taxes, housing, food, transport, insurance and other costs.
If your income increases by 5% while the cost of the things you regularly pay for rises by a similar amount, much of the improvement can disappear.
That gives us two different ideas:
Nominal salary: the number on your paycheck.
Real purchasing power: what the money can actually buy.
The raise was real. So were the higher bills.
Nominal Salary vs Real Salary
Suppose your salary rises from:
€40,000 to €42,000
That is a 5% nominal increase.
Now imagine that prices relevant to your household also rise by approximately 5% over that period.
In a simplified example, the number on your salary has increased, but your purchasing power may have changed very little.
This is essentially the distinction economists make between nominal and real values. The European Central Bank explains that inflation reduces purchasing power because the same amount of money buys fewer goods and services as prices rise. Investor
There is an important complication, though: headline inflation is not necessarily your inflation.
Your Personal Cost Mix May Be Different From “Inflation”
Inflation measures such as the Harmonised Index of Consumer Prices used in the EU are based on a broad basket of goods and services. Eurostat explains that different categories are weighted according to their importance in household spending. S&P Global
Your household does not necessarily resemble that average basket.
Imagine two people.
Person A spends a large proportion of income on rent, groceries and energy.
Person B owns a home outright and spends more on travel, entertainment and electronics.
If housing and food become substantially more expensive while electronics barely change, Person A may feel much more pressure even though both people read the same headline inflation figure.
That does not require inventing a formal personal inflation index. It simply means that the mix of things you actually buy matters.
This is one reason someone can receive a raise that looks respectable on paper and still feel financially squeezed.
A Raise Can Look Bigger in Gross Pay Than in Your Bank Account
There is another gap between the salary increase announced by your employer and the extra money you actually receive.
Suppose your gross salary rises by:
€300 per month
That does not necessarily mean €300 more arrives in your bank account.
Depending on the country and your circumstances, gross earnings can be subject to income tax, social-security contributions, pension contributions, healthcare costs and other payroll deductions.
The exact treatment varies substantially between countries.
Gross salary is not spending money.
For German employees specifically, Crown Altessa’s guide to gross vs net salary in Germany explains how gross pay becomes take-home pay. The principle here is broader: when measuring whether a raise improved your life, compare the change in net income, not just the headline gross increase.
The Raise Disappears One Expense at a Time
Consider this hypothetical monthly example.
Before the raise:
Net income: €2,300
After the raise:
Net income: €2,550
You genuinely have €250 more take-home pay.
Now look at what happened elsewhere:
| Change | Monthly increase |
|---|---|
| Rent | +€100 |
| Groceries | +€50 |
| Utilities and insurance | +€35 |
| Transport | +€25 |
| Subscriptions and services | +€20 |
| Total additional costs | +€230 |
Your income improved by €250.
Your recurring costs increased by €230.
The amount of additional breathing room you actually feel is:
€20 per month.
Nothing mysterious happened to the raise.
It was absorbed one expense at a time.
Housing Can Swallow a Raise Very Quickly
Housing deserves particular attention because it is often one of a household’s largest recurring expenses.
Suppose your take-home pay improves by €150 per month.
Then your rent rises by €150.
Your income is objectively higher, but your available monthly margin has not improved.
The exact housing pressures vary enormously by location and household. This is also why national inflation figures can feel disconnected from someone’s lived experience.
For readers dealing specifically with German housing costs, Crown Altessa’s guide to the upfront costs of renting an apartment in Germany covers deposits and other housing expenses separately.
Fixed Costs Are More Important Than They Look
Large increases attract attention. Small recurring ones are easier to miss.
Your internet plan rises €5.
Insurance rises €9.
A streaming service adds €3.
Your phone contract changes.
Transport costs increase.
Childcare becomes more expensive.
One new subscription appears.
Individually, none feels capable of consuming a raise.
Together, they can.
A €10 increase across eight recurring expenses means €80 less monthly flexibility. Because these expenses repeat, you do not feel them as one dramatic €960 annual bill. You experience them as a slightly tighter month, every month.
Lifestyle Creep Can Be Real — but Don’t Blame Everything on It
Spending often changes when income increases.
You might eat at better restaurants, travel more often, upgrade your phone, move into a nicer apartment or start paying for conveniences you previously avoided.
That is commonly described as lifestyle creep or lifestyle inflation.
But it is too easy to use lifestyle creep as the explanation for everything.
There is a major difference between:
Voluntary lifestyle inflation: choosing a more expensive lifestyle as income rises.
and:
Unavoidable cost inflation: paying more for broadly the same essentials.
Someone can maintain similar habits and still find that rent, groceries, insurance and transport consume more of their income.
Crown Altessa’s article on why saving money feels increasingly difficult when living costs rise looks more closely at that cost-pressure problem in Germany. The important point here is that a disappearing raise can have both behavioural and external causes.
Small Upgrades Can Quietly Become Permanent Expenses
A raise often triggers several individually reasonable decisions.
Suppose that after a promotion you add:
- €15 for another streaming service
- €40 for a better gym membership
- €80 more each month for eating out
- €50 for phone financing
- €100 for a nicer apartment
Total:
€285 per month
None of those choices is automatically irresponsible.
But if your net raise was €300, you have converted almost the entire increase into recurring spending.
Your lifestyle improved.
Your financial flexibility barely did.
That distinction matters because recurring commitments behave differently from one-off treats. They follow you into the next month.
Savings Can Make You Feel Poorer Even When You’re Doing Better
There is another possibility that is easy to overlook.
Before your raise:
Savings: €100 per month
After your raise:
Savings: €350 per month
Increase in take-home pay:
€250
Your day-to-day spending money feels exactly the same.
You might reasonably think:
“I got a raise, but I don’t feel any richer.”
In one sense, that is true. Your discretionary lifestyle did not change.
Financially, however, something significant happened: you are now putting an additional €3,000 per year into savings.
The raise did not disappear.
It changed jobs.
The same can happen when additional income goes toward investments, pension contributions or faster debt repayment.
Some raises disappear into costs. Others disappear into progress.
Debt Payments Can Absorb Income Growth Too
A raise may also coincide with new financial obligations.
Perhaps you financed a car, accumulated a credit-card balance, took a personal loan or added buy-now-pay-later commitments.
Even if income rose first, the new repayments can consume the improvement later.
That creates another reason to distinguish salary from available monthly margin.
If debt and cash reserves are competing for the same extra income, the relevant question becomes more specific.
Taxes, Benefits and Threshold Effects Can Matter
Higher gross income does not always translate proportionally into higher disposable income.
Depending on the country and individual circumstances, an increase in earnings can affect taxes, social contributions, means-tested benefits, subsidies, childcare support or other income-linked programmes.
This does not mean that receiving a raise automatically makes someone worse off or that everyone loses benefits when income rises.
It means only that the gross raise is not always the correct number to use when asking how much your financial position improved.
Start with the actual change in take-home resources.
Why a 10% Raise May Not Feel Like 10%
Percentages on salary can sound much larger than the change in everyday flexibility.
Suppose you previously had:
€600 per month left after essential costs.
A raise increases take-home pay by:
€200
But your essential monthly costs have also increased:
€150
Your new amount after essentials is:
€650
Your paycheck improved by €200.
Your actual monthly breathing room improved by only:
€50.
That is why someone can receive a meaningful salary increase without experiencing an equally meaningful improvement in daily life.
The Difference Between Income and Margin
This may be the most useful way to think about the entire problem.
Income: what comes in.
Margin: what remains after essential and committed costs.
Consider two people.
Person A
Net income:
€3,000
Committed expenses:
€2,800
Margin:
€200
Person B
Net income:
€2,500
Committed expenses:
€1,800
Margin:
€700
Person A earns €500 more.
Person B has €500 more room each month.
Who feels financially more comfortable?
Salary alone cannot answer that.
Salary tells you how much enters the system. Margin tells you how much freedom the system has.
A structured way of separating those flows is covered in Crown Altessa’s guide to managing your personal finances.
Track Your Raise, Not Just Your Salary
When you receive a meaningful raise, save a snapshot of your finances.
Record your:
- take-home pay
- housing
- food
- transport
- insurance and utilities
- debt payments
- subscriptions
- savings or investments
- genuinely discretionary money
Then compare the same categories six months or a year later.
You are trying to answer five questions:
How much of my raise went to higher essential costs?
How much went to lifestyle upgrades?
How much went to saving or investing?
How much went to debt or other new obligations?
How much actually increased my disposable monthly margin?
That is a much better answer to “Where did my raise go?” than simply comparing two annual salary figures.
A Simple “Where Did My Raise Go?” Example
Here is a hypothetical before-and-after comparison:
| Monthly category | Before | After |
|---|---|---|
| Net income | €2,300 | €2,550 |
| Rent | €800 | €900 |
| Food | €350 | €400 |
| Utilities/insurance | €250 | €285 |
| Transport | €150 | €175 |
| Debt | €100 | €100 |
| Savings | €200 | €300 |
| Discretionary money | €450 | €390 |
The arithmetic balances in both columns.
Before:
€2,300 − €1,850 = €450
After:
€2,550 − €2,160 = €390
The person earns €250 more each month.
They also save €100 more.
Yet the money available for discretionary spending has actually fallen by €60.
This person is simultaneously earning more, saving more and feeling more financially constrained.
Those statements can all be true.
When a Raise Really Is a Raise
Suppose take-home pay increases:
+€300
Meanwhile, essential costs increase:
+€100
Additional monthly margin:
+€200
Now the raise has produced a clear improvement in financial flexibility.
You can decide what that extra €200 should do: improve your lifestyle, strengthen savings, reduce debt, invest, fund a goal or combine several priorities.
Crown Altessa’s guide to how much of your salary to save examines that allocation question separately for workers in Germany.
The important point here is that the margin actually expanded.
How to Stop Every Raise From Disappearing
When your next raise arrives, first identify the actual net increase, not merely the gross percentage announced.
Then compare it with any essential costs that have already risen.
After that, decide intentionally what part of the remaining increase should improve your lifestyle, what part should strengthen savings or investments, and whether debt deserves some of it.
There is no universal percentage that needs to go into each category.
But preserving at least some genuine increase in monthly flexibility can make a raise feel like an improvement rather than merely a larger number on a payslip.
Should You Avoid Lifestyle Upgrades Completely?
No.
Earning more is partly valuable because money can improve life.
A better apartment, more travel, hobbies, restaurants or greater convenience can be legitimate uses of higher income.
The issue is not allowing yourself to enjoy a raise.
It is allowing every increase in income to become a permanent increase in recurring expenses without noticing.
If your lifestyle improves intentionally and you are comfortable with the trade-off, the money has not mysteriously disappeared. You chose what the raise would buy.
Three Raise Scenarios
Case A: Higher Costs Absorb Most of It
Net raise:
€200 per month
Essential costs rise:
€180
Improvement in monthly margin:
€20
The raise is real, but most of it is absorbed by higher costs.
Case B: Lifestyle Creep Absorbs It
Net raise:
€300
Essential costs remain broadly unchanged.
New discretionary commitments:
€290
Additional flexibility:
€10
Life may be more comfortable, but financial margin barely improves.
Case C: The Raise “Disappears” Into Savings
Net raise:
€250
Savings contribution increases:
€200
Discretionary spending increases:
€50
The person may not feel dramatically richer, but their financial position is strengthening.
Common Misconceptions
“My salary rose, so I must be richer.”
Not necessarily in purchasing-power or monthly-margin terms.
“If I still feel squeezed, I must be bad with money.”
Not necessarily. Essential costs may have absorbed much of the increase.
“Inflation is the only reason raises disappear.”
No. Taxes, fixed costs, lifestyle changes, debt and increased saving can all matter.
“A 5% raise means 5% more spending money.”
A gross salary increase is not the same as a 5% increase in discretionary cash.
“Lifestyle creep caused everything.”
Sometimes it contributes. Sometimes unavoidable expenses are the larger factor.
“Saving more means my raise disappeared.”
The money left your spending budget, but it increased your savings.
“Gross salary tells me how much better off I am.”
Gross income is useful, but take-home pay and remaining financial margin tell you more about everyday flexibility.
A Five-Minute Salary Reality Check
Compare the last time you received a meaningful raise with today:
- What was my old net monthly income?
- What is my current net monthly income?
- How much did housing change?
- How much did food change?
- How much did transport change?
- How much did insurance and utilities change?
- Did I add new debt, financing or subscriptions?
- Am I saving or investing more?
- How much genuinely discretionary money did I have then?
- How much do I have now?
The difference between questions 9 and 10 is often more revealing than the difference between your old and new gross salaries.
Frequently Asked Questions
Why Does My Salary Feel Smaller Even After a Raise?
Your take-home pay may have increased while housing, food, transport, insurance, fixed costs or debt payments also increased. Part of the raise may also be going toward savings or lifestyle upgrades.
What Is the Difference Between Nominal Salary and Real Salary?
Nominal salary is the monetary amount you earn. Real income adjusts conceptually for changes in purchasing power, helping show whether the higher amount can actually buy more.
Can Inflation Cancel Out a Pay Raise?
It can absorb much or even all of the purchasing-power improvement from a raise, but the effect depends on the size of the raise and the prices relevant to your household.
Why Do I Earn More but Save Less?
Your essential costs, debt payments or discretionary spending may have risen faster than your take-home income. Comparing old and current monthly categories can reveal where the difference went.
Why Does a 10% Raise Not Feel Like 10%?
The percentage may refer to gross salary, while your daily experience depends on the net increase and how much remains after higher living costs.
Does Lifestyle Creep Explain Why My Raise Disappeared?
Sometimes, but not always. Voluntary spending upgrades and unavoidable increases in essential costs should be separated rather than treating all higher spending as lifestyle creep.
How Can I Tell Whether I Am Actually Better Off After a Raise?
Compare your old and current take-home income, essential costs, debt, savings and discretionary margin. If more money remains after your obligations, your financial flexibility has genuinely improved.
Conclusion
Return to the original example.
Old salary:
€40,000
New salary:
€46,000
The €6,000 increase is real.
But that number alone cannot tell you whether life became €6,000 easier.
You need to know what happened to your take-home pay, housing, food, transport, insurance, fixed costs, debt, savings and discretionary margin while your salary was increasing.
For a broader beginner-friendly framework for organising those parts of your finances, Personal Finance Made Simple for Beginners is available on Gumroad and Amazon.
A raise tells you that your income increased. Your remaining margin tells you whether your financial life actually improved.
Feeling financially stuck?
When financial pressure becomes constant, long-term decisions start feeling emotionally heavy.
The Crown Altessa newsletter was created to help people rebuild clarity slowly and strategically through practical financial frameworks, long-term thinking, and structured decision-making insights.
Join the newsletter and receive:
• the free Financial Foundation Guide
• strategic financial insights
• practical tools for long-term stability
• frameworks designed to reduce financial overwhelm
Start building financial clarity one step at a time.