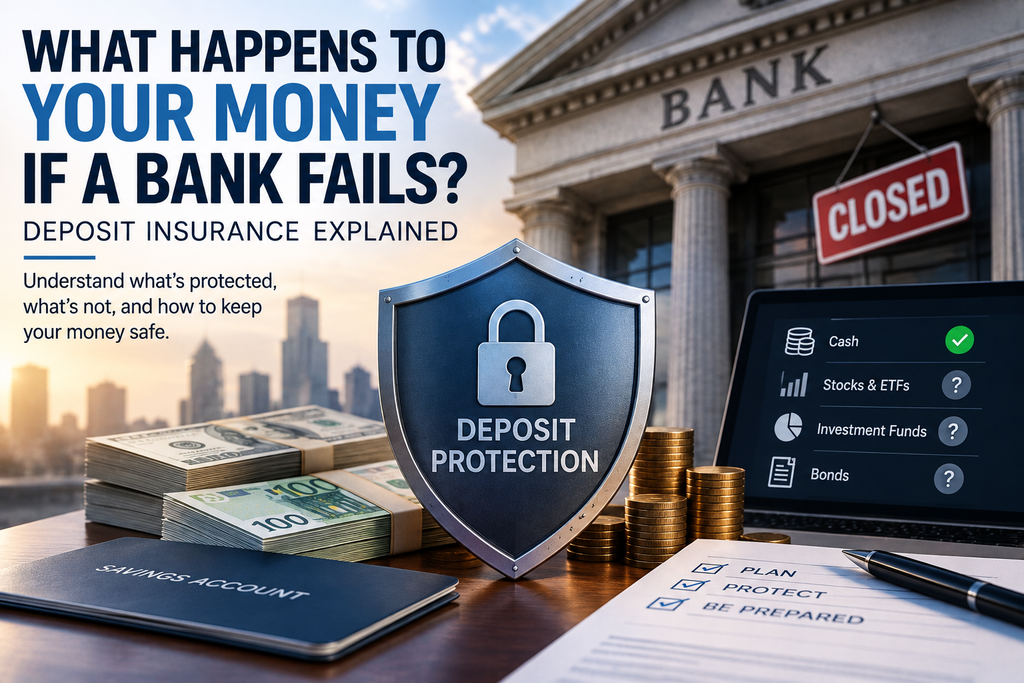
Imagine opening the news and discovering that your bank has failed.
You have €20,000 or $20,000 sitting in your account.
What happens next?
Does the balance disappear?
Can you still access it?
Does the government reimburse you?
For many ordinary depositors, a bank failure does not automatically mean losing all the money in the account.
Many countries operate statutory deposit-insurance or deposit-guarantee systems designed to protect eligible deposits up to a specified limit when a covered bank fails.
But four details matter enormously:
- where the bank is regulated;
- how much money you hold;
- what type of financial product it is;
- how the account is legally owned.
That last point is particularly important because cash in a bank account, stocks in a brokerage account and money sitting inside an investment app may look similar on a screen while having very different legal protection.
What Actually Happens When a Bank Fails?
A bank failure does not always follow one identical script.
Depending on the country and circumstances, regulators may:
- close the institution;
- place it into resolution;
- arrange a sale to another bank;
- transfer customer deposits;
- pay insured deposits through a deposit-guarantee system;
- manage the remaining assets and liabilities through an insolvency or receivership process.
In the United States, for example, the FDIC may arrange for a healthy bank to assume the failed bank’s insured deposits. If no acquiring bank is available, the FDIC can pay insured depositors directly.
The European Union likewise requires national deposit-guarantee schemes to protect eligible deposits under a harmonised framework.
So the practical question is not simply:
“Did the bank fail?”
It is:
“Was my money an eligible deposit, and was it within the applicable protection limit?”
Deposit Insurance: The Basic Idea
Deposit insurance or a deposit guarantee is a financial safety mechanism.
In simple terms:
A statutory protection system covers eligible deposits up to a defined limit if a participating bank fails.
The protection is normally attached to qualifying bank deposits.
It does not automatically insure every financial product a bank happens to sell.
That distinction prevents a common misunderstanding.
Imagine your bank offers:
- a current account;
- a savings account;
- an investment fund;
- stocks;
- bonds.
All five products may appear inside the same banking app.
That does not make them legally identical.
The cash account may fall under statutory deposit protection.
The investments usually do not.
What Is Usually Considered a Bank Deposit?
Depending on the jurisdiction, familiar deposit products can include:
- current or checking accounts;
- savings accounts;
- money-market deposit accounts in the U.S.;
- fixed or term deposits;
- certificates of deposit in the U.S.
The FDIC explicitly lists checking accounts, savings accounts, money-market deposit accounts and time deposits such as CDs among insured deposit products at covered institutions.
By contrast, products such as:
- stocks;
- ETFs;
- bonds;
- mutual funds;
- investment funds;
- cryptocurrencies
do not become insured bank deposits merely because you bought them through a bank.
The FDIC specifically excludes stocks, bonds and mutual funds from deposit insurance.
This is also why understanding the difference between cash and long-term assets matters in your broader financial structure. Crown Altessa’s personal finance system guide explores how different pools of money can have different jobs.
How Deposit Protection Works in the United States
For deposits at an FDIC-insured institution, the standard insurance amount in 2026 remains:
$250,000 per depositor, per insured bank, per ownership category.
That wording matters.
The limit is not simply:
“$250,000 per account.”
The FDIC aggregates deposits held by the same depositor, at the same insured bank, within the same ownership category. Different qualifying ownership categories can receive separate coverage under the rules.
Simple example
Suppose you have:
$100,000 in an individual savings account
at one FDIC-insured bank.
Assuming the account is otherwise eligible, it falls below the $250,000 standard insurance limit for that ownership category.
Now suppose you have:
$300,000 in a single individual deposit account
at the same bank.
Conceptually:
$250,000 may fall within the standard insurance limit.
The remaining $50,000 would be above that standard limit, assuming no other ownership-category rules increase the available protection.
That $50,000 is not automatically guaranteed by FDIC deposit insurance.
How Deposit Protection Works in the European Union
The European Union uses a different framework, but the underlying principle is similar.
EU rules currently provide harmonised deposit protection of:
€100,000 per depositor per bank.
National deposit-guarantee schemes implement that protection across EU member states.
Suppose you hold:
€70,000 in eligible deposits at one covered bank.
That amount falls below the general €100,000 limit.
Now suppose you hold:
€150,000 in eligible deposits at one bank.
Conceptually:
€100,000 falls within the standard guarantee.
The remaining €50,000 is above the ordinary protected limit.
EU rules can provide enhanced temporary protection above €100,000 in certain specific circumstances defined by law, including some balances connected with major life events or private residential-property transactions. Those rules are more specialised and can depend on national implementation.
For ordinary planning, however, the core EU figure is €100,000 per depositor per bank.
What If You Have More Than the Insured Limit?
This is where bank-failure risk becomes more nuanced.
Suppose:
Bank balance: €150,000
Standard applicable protection:
€100,000
It would be inaccurate to say:
“You definitely lose €50,000.”
But it would also be inaccurate to say:
“Don’t worry, you’ll definitely get the extra €50,000 back.”
The portion above the statutory guarantee may become an uninsured claim exposed to the bank’s resolution or insolvency process.
The eventual recovery can depend on:
- the failed bank’s remaining assets;
- how authorities resolve the institution;
- creditor priority;
- applicable insolvency law;
- the jurisdiction.
In the U.S., the FDIC explains that uninsured depositors can receive a claim against the failed bank’s receivership and may recover part of that claim as assets are liquidated. Recovery can take time and is not guaranteed to equal the full uninsured balance.
So the correct mental model is:
Insured balance = statutory protection applies.
Uninsured balance = recovery becomes uncertain.
That difference is one reason large cash balances deserve more attention than everyday checking-account balances.
Do Multiple Accounts at the Same Bank Increase Protection?
Not necessarily.
Imagine you have at one bank:
- €40,000 in a current account;
- €40,000 in savings;
- €40,000 in a term deposit.
You have three account numbers.
That does not necessarily mean you have three separate €100,000 guarantees.
Under the EU framework, deposits belonging to the same depositor at the same credit institution are aggregated for the €100,000 limit. The official depositor-information template explicitly notes that multiple deposits at the same institution are added together.
The United States follows a similar principle within each ownership category: accounts in the same ownership category at the same FDIC-insured bank are combined for insurance purposes.
Another complication is branding.
Two different bank names do not always mean two separate licensed institutions.
A financial group may operate more than one brand under the same banking licence.
So when assessing protection, identify the legal institution, not merely the logo displayed in the app.
What About Accounts at Different Banks?
Protection limits generally apply separately to genuinely distinct covered institutions.
In the U.S., the FDIC explicitly states that deposits held at separately chartered insured banks receive separate insurance limits.
The EU framework similarly applies the €100,000 standard limit per depositor per credit institution.
So:
€80,000 at Bank A
and
€80,000 at a genuinely separate Bank B
can produce a different protection position from:
€160,000 at Bank A alone.
But again, two brands are not necessarily two legal banks.
Verify the institution actually holding the deposits.
This is concentration risk in a very practical form: not all financial resilience comes from earning more or investing more. Sometimes it comes from understanding where your existing money is legally exposed. Crown Altessa’s article on building financial confidence under uncertainty explores that broader decision-making principle.
What Happens to Stocks and ETFs If a Bank Fails?
Stocks and ETFs are not ordinary bank deposits.
If securities are legally held for you through a brokerage or custody arrangement, they generally represent customer-owned investment assets rather than simply money you lent to the bank as a deposit.
So:
Bank failure does not automatically mean your stocks or ETFs disappear.
But that does not mean every jurisdiction handles securities custody identically.
A failure can still create:
- temporary loss of account access;
- transfer delays;
- administrative complications;
- reconciliation of ownership records;
- insolvency proceedings where something has gone wrong with custody.
The key distinction is:
A €50,000 savings account is a bank deposit.
€50,000 of ETFs held in custody is an investment portfolio.
Those assets face different risks and different protection frameworks.
This is one reason personal finance works better when cash reserves and long-term investments are deliberately separated rather than treated as interchangeable balances.
What If Your Brokerage Fails Instead?
A brokerage failure is a different problem from a bank failure.
Brokerage systems commonly involve rules designed to separate client securities from the broker’s own assets, but the exact legal mechanics depend on the country.
The United States provides a useful example.
The Securities Investor Protection Corporation, or SIPC, can step in when a SIPC-member brokerage fails and customer cash or securities are missing.
Its current limit is:
up to $500,000 per customer, including a maximum of $250,000 for cash.
But SIPC is not investment-loss insurance.
If you buy shares for $50,000 and their market value falls to $20,000, SIPC does not reimburse the $30,000 decline.
It also does not guarantee investment performance or compensate you because you selected a bad investment.
Its role is primarily about missing customer cash and securities when a covered brokerage fails.
That distinction is essential:
FDIC protects eligible U.S. bank deposits against bank failure.
SIPC addresses certain missing customer assets in a failed SIPC-member brokerage.
They solve different problems.
What About Cash Sitting in an Investment App?
This is one of the most important questions in modern finance.
You open an investment app and see:
Cash: €12,000
Where is that €12,000 actually held?
The answer depends on the platform.
Uninvested money might be held:
- by a partner bank;
- across several partner banks;
- directly within a brokerage structure;
- in a money-market fund;
- through another custodial arrangement.
Those structures are legally different.
A money-market fund, for example, is an investment, not simply a bank deposit, even if the app presents the balance in a cash-like way.
A bank sweep arrangement may instead place money into deposit accounts at partner banks, potentially bringing bank-deposit protection rules into play.
Before assuming investment-app cash is insured, check:
- Which legal institution holds the money?
- Is it legally a bank deposit or an investment product?
- Which protection scheme applies?
- What protection limit applies?
- Is the money spread across more than one bank?
- Are your other deposits at those same banks aggregated with it?
The visual simplicity of an app does not determine the legal structure underneath it.
How Quickly Do Depositors Get Their Money Back?
There is no universal global timeframe.
In the United States, the FDIC says its goal is to provide insured depositors access to protected funds within two business days of a bank failure. Frequently this happens through transfer to an acquiring bank rather than a separate insurance payment. Some more complicated accounts can take longer while coverage is determined.
In the European Union, the Deposit Guarantee Schemes Directive provides for reimbursement of covered deposits within seven working days under the current framework.
Operational circumstances can still differ from one failure to another.
That is another reason having all immediately accessible money dependent on one institution can create inconvenience even where the balance is ultimately protected.
Can Governments Protect More Than the Normal Limit?
Sometimes authorities take extraordinary measures during exceptional financial-stability events.
That has happened historically.
But personal financial planning should not assume that politicians or regulators will expand protection beyond the statutory rules every time a bank encounters problems.
The sensible baseline is the protection actually established by law before a crisis.
Extraordinary intervention is a possibility.
It is not a personal deposit-insurance strategy.
How to Check Whether Your Money Is Protected
You do not need to wait for a banking crisis to understand your position.
Use this checklist.
1. Identify the legal bank
Look beyond the app or brand name.
Find the actual regulated institution holding the deposit.
2. Confirm participation in the official protection system
For the U.S., verify FDIC-insured status.
In the EU, identify the applicable national deposit-guarantee scheme.
3. Check the current limit
At present:
United States FDIC: $250,000 per depositor, per insured bank, per ownership category.
European Union: €100,000 per depositor per bank under the harmonised framework.
4. Add together eligible deposits at the same institution
Do not count account numbers.
Count your total eligible exposure under the applicable ownership rules.
5. Check ownership
Individual, joint, trust and other ownership structures can affect coverage.
Do not create structures solely from a simplified article; check the official rules.
6. Separate deposits from investments
Savings account?
Deposit.
ETF?
Investment.
They are not the same.
7. Check investment-platform cash
Find out whether it is:
- bank cash;
- brokerage cash;
- a money-market product;
- another structure.
8. Keep records
Retain account statements and information identifying the institution holding your money.
A structured approach like this fits naturally into a broader personal finance management system: financial organisation is partly about knowing not just how much money you own, but where it sits and what rules apply to it.
Should You Spread Large Cash Balances Across Banks?
Someone holding cash materially above the applicable statutory protection limit may reasonably consider concentration risk.
That does not mean everyone needs five bank accounts.
An individual with €8,000 of savings has a very different issue from someone holding €400,000 of short-term cash.
The useful question is not:
“How many bank accounts should I own?”
It is:
“How much uninsured exposure am I comfortable having to one institution?”
If the answer is unclear, first calculate how much eligible cash is actually aggregated at each legal bank.
Only then can you see whether concentration exists.
Broader financial stability is also about proportion rather than fear. Crown Altessa’s article on building stability when financial conditions change explores the role of liquidity within a wider financial foundation.
Common Bank-Failure Misconceptions
“If a bank fails, everyone loses everything.”
False. Eligible deposits may be protected up to the applicable statutory limit.
“Every account gets its own insurance limit.”
Not generally. Deposits can be aggregated at the same institution.
“Two brands automatically mean two banks.”
Not necessarily. Check the licensed institution.
“Stocks sold by my bank are deposit-insured.”
No. Investment products are not bank deposits simply because a bank sells them.
“Deposit insurance protects me if my ETF falls in value.”
No. Normal investment losses are not deposit-insurance claims.
“Any money above the limit is guaranteed to disappear.”
No. Uninsured balances can potentially recover something through resolution or insolvency, but the result is uncertain.
Frequently Asked Questions
What Happens to My Money If My Bank Fails?
Eligible bank deposits may be transferred to another institution or repaid through the applicable deposit-protection scheme up to the statutory limit. Amounts above the protected limit can become claims in the resolution or insolvency process.
How Much Money Is Protected If a Bank Fails?
In the United States, the standard FDIC limit is $250,000 per depositor, per insured bank, per ownership category. In the EU, the harmonised standard is €100,000 per depositor per bank.
Is Money in a Savings Account Insured?
It can be if the account is an eligible deposit at a covered institution and falls within the applicable limits and ownership rules.
Do Multiple Accounts Increase Deposit Protection?
Not simply because there are multiple account numbers. Accounts at the same legal bank can be aggregated. In the U.S., separate qualifying ownership categories can create separate coverage.
What Happens if I Have More Than the Insured Limit?
The protected portion falls within the applicable guarantee. The excess can become uninsured exposure in the bank’s resolution or insolvency process. Some recovery may occur, but it should not be assumed.
What Happens to My Stocks if My Bank Fails?
Stocks or ETFs held through a proper brokerage or custody arrangement are conceptually different from bank deposits and do not automatically disappear because the bank fails. The exact custody and insolvency rules depend on jurisdiction.
Is Cash in a Brokerage Account Insured?
It depends on how the cash is legally held. In the U.S., qualifying cash held for securities transactions at a SIPC-member brokerage can receive SIPC protection within its limits. Cash swept to a bank may instead fall under bank-deposit protection. Other structures can work differently.
Conclusion
If a bank fails, the outcome is not automatically:
“Your money is gone.”
For ordinary eligible deposits, statutory protection may cover your balance up to the applicable limit.
Uncertainty becomes more important when:
- cash exceeds those limits;
- large balances are concentrated at one institution;
- several accounts are incorrectly assumed to have separate protection;
- an investment is mistaken for a bank deposit;
- cash inside an investment platform has a more complicated legal structure.
The most useful question is therefore not simply:
“Is my money in a bank?”
It is:
“Which legal institution holds it, what type of asset is it, and what protection actually applies?”
For a broader beginner-friendly foundation for organising cash, savings and investments, Personal Finance Made Simple for Beginners is available on Gumroad and Amazon.
My book on Gumroad:
https://ukandu0.gumroad.com/l/bteyh
Or on Amazon:
Feeling financially stuck?
When financial pressure becomes constant, long-term decisions start feeling emotionally heavy.
The Crown Altessa newsletter was created to help people rebuild clarity slowly and strategically through practical financial frameworks, long-term thinking, and structured decision-making insights.
Join the newsletter and receive:
• the free Financial Foundation Guide
• strategic financial insights
• practical tools for long-term stability
• frameworks designed to reduce financial overwhelm
Start building financial clarity one step at a time.